Family loses home over $2,200 tax debt — Supreme Court steps in
A Michigan family lost its house over roughly $2,200 in unpaid property taxes, only to see the county sell it for far less than its assessed value and keep every dollar. Their fight has now reached the Supreme Court, which is being asked to decide how far government can go when it forecloses on a home to collect a small debt.
The case follows a landmark ruling involving a 94-year-old grandmother from Minnesota, where the Court held that local officials cannot keep more than a taxpayer owes when they seize and sell a home. Together, the two disputes test how firmly the Constitution protects home equity and how much protection families can expect when a tax bill spirals out of control.
How a $2,241 tax bill cost a Michigan family their house

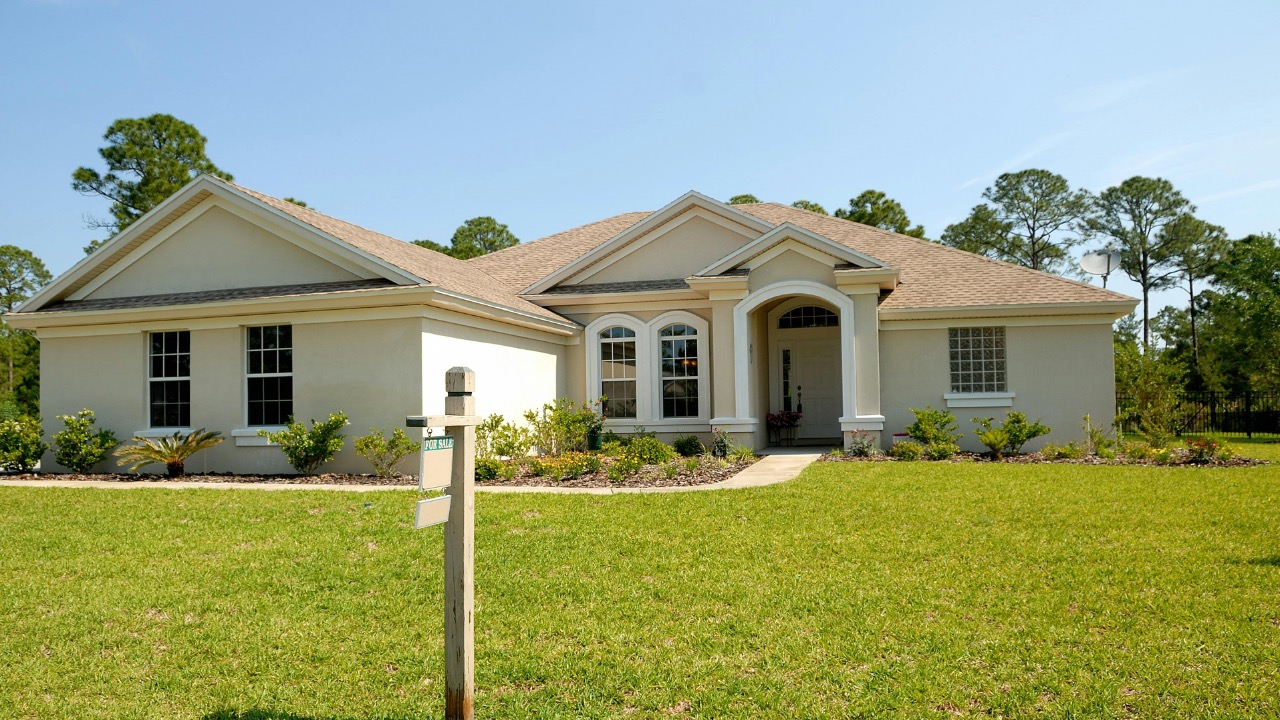
When Isabella County government in Michigan moved against the Pung family, the unpaid balance was only $2,241 in property taxes. County officials eventually took title to the ranch-style home, then sold it for nearly $120,000 below what local records said it was worth. According to one account, the home was sold for nearly $120,000 below its assessed value to satisfy a $2,241 tax obligation, and the family received nothing from the sale. The report describes how When Isabella County officials disposed of the property, they treated the entire remaining equity as government revenue.
Another detailed account identifies the homeowner as Michael Pung and explains that his family lost their ranch-style residence in Isabella County to cover $2,242 in unpaid taxes. That report notes that the case from Michigan’s Isabella County centers on the fact that the home was taken to satisfy $2,242 in tax debt and then sold, with the government keeping everything. The description of how the property was Sold for far less than its assessed value underscores the financial loss for the family.
The dispute is not simply about whether Isabella County followed state tax foreclosure procedures. It is about whether the county had the right to keep the entire value of the house, including the equity that far exceeded the tax debt, interest, penalties, and costs. The family argues that once the $2,241 or $2,242 in taxes and associated charges were covered, the Constitution required the government to return the surplus value to the former owners.
What the Supreme Court is being asked to decide in the Pung case
At the Supreme Court, the Pung case is framed as a test of both property rights and the limits of government punishment. A filing from NTUF’s Taxpayer Defense Center describes how the home was later sold for its true worth, listed as $194,400, and contends that taking the entire property to pay roughly $2,000 in taxes functions as an excessive penalty. The brief argues that the government should not be allowed to keep a house that was eventually worth $194,400 in order to satisfy such a small debt, and that this kind of forfeiture should be treated as an excessive fine. The document from NTUF presses the Court to recognize that dynamic.
Coverage of the pending arguments explains that the U.S. Supreme Court will hear a challenge against Michigan officials over whether the family is owed compensation for the equity that remained after the tax debt was paid. Reporter Katherine Dailey notes that the Supreme Court is set to consider a case against Mich officials that could determine whether counties must pay back former owners when they keep more than the tax bill required. The description of how the Supreme Court will decide if a Michigan family is owed by the county puts the stakes in clear terms.
A separate legal analysis points out that Isabella County will appear before the Supreme Court later this year and that the justices are expected to address not just whether excess equity belongs to the former owner, but how much that owner is owed. The summary explains that while Tyler v. Hennepin County asked whether excess equity belongs to the taxpayer, the new case from Isabella County will focus on how much that property owner is owed. The description of how Isabella County will go before the Supreme Court highlights that this is the next phase in defining remedies for what critics call home equity theft.
Inside the argument: excessive fines and home equity theft
The Pung family and their supporters describe the practice at the center of the case as home equity theft. One advocacy group defines home equity theft as what happens when the government takes a home to satisfy a tax debt and then keeps the entire value, including the surplus beyond what the taxpayer owes. A detailed FAQ explains that home equity theft occurs when the government seizes a property for unpaid taxes, sells it, and retains the full sale proceeds instead of returning the remaining equity to the former owner. That explanation appears in a resource titled Frequently asked questions about Tyler v. Hennepin County, which lays out how the practice works.
During oral argument in the Michigan case, members of the Court probed whether the loss of the Pung home should be treated as a fine. One account quotes Justice KETANJI BROWN JACKSON, who suggested that if Mr Pung wanted to get the maximum value of the house to cover the debt, he could have sold it himself, and questioned whether the county’s actions should be seen as punishment. The same report notes that Justice Amy Coney Barrett appeared skeptical of the county’s position and that Justice Elena Kagan pressed lawyers on what would count as an excessive fine. The description of how KETANJI BROWN JACKSON framed the question illustrates how the justices are wrestling with the boundary between tax collection and punishment.
Supporters of the Pung family argue that when the government takes a home worth far more than the tax debt and keeps the difference, it functions like a fine that can be excessive under the Eighth Amendment. They also argue that the practice violates long-standing property principles that treat equity as a protected interest belonging to the owner, not the state. On the other side, counties and some state officials contend that clear foreclosure statutes give them authority to extinguish the owner’s interest once deadlines pass, and that former owners had opportunities to avoid forfeiture by paying or selling earlier.
The Minnesota case that changed the law: Tyler v. Hennepin County
The Pung case does not arrive in a vacuum. It follows a unanimous Supreme Court ruling in Tyler v. Hennepin County, a dispute that began when a 94-year-old woman lost her Minnesota condominium over unpaid taxes. According to a detailed case summary, ninety-four-year-old Geraldine Tyler owned a one-bedroom unit in Hennepin County, Minnesota and fell behind on her property taxes. The description of how Tyler v. Hennepin County, Minnesota, et al. unfolded explains that the county eventually seized and sold her home, then kept more than she owed.
In that case, the Supreme Court held that the State of Minnesota violated the Takings Clause when it kept the surplus equity from the sale. A legal analysis notes that in Tyler v. Hennepin County, a unanimous U.S. Supreme Court concluded that the State of Minnesota violated a property owner’s constitutional rights by retaining value beyond the tax debt. The explanation of how In Tyler v. Hennepin County the Court found a violation under the Fifth Amendment sets the constitutional backdrop for the Michigan dispute.
The official case materials describe how Geraldine Tyler owned a condominium in Minneapolis, stopped paying her property taxes, and accumulated a tax debt that the county sought to collect through forfeiture. The summary explains that Geraldine Tyler owned a condominium in Minneapolis, that She stopped paying her property taxes, and that the resulting tax debt triggered a forfeiture process. The account from Facts of the case notes that the Court ultimately issued a unanimous decision for Tyler.
Another detailed review sets out the procedural history and the Court’s holding. It notes that the case, titled Tyler v. Hennepin County, Minnesota, carried a specific Docket No and reached the Court from the 8th Cir. The same analysis explains that the Holding was that Geraldine Tyler plausibly alleges that Hennepin County violated the Takings Clause by keeping more than she owed. The description of how Tyler v. Hennepin County, Minnesota reached the Supreme Court shows how the justices framed the core question.
A separate case summary notes that the Court’s opinion was unanimous and that it rested on the Takings Clause of the Fifth Amendment. It explains that in a unanimous opinion, the Court held that the government cannot take more from a taxpayer than she owes and that the forfeiture of Tyler’s surplus equity violated the Takings Clause. That summary from the Hennepin County materials emphasizes that the Court also left open whether such forfeitures might be excessive fines.
How Tyler reshaped state laws and tax foreclosure practices
The Tyler decision immediately put pressure on states that allowed counties to keep surplus equity in tax foreclosure cases. An overview of the ruling notes that on May 25 the United States Supreme Court, in Tyler v. Hennepin County, ruled that it is unconstitutional for a county to retain more than a taxpayer owes after selling a tax-foreclosed home. The analysis of the Hennepin County Decision explains that the case involved a relatively modest tax debt plus about $13,000 in interest and fees, compared with the full value of the property.
Another summary of the Court’s reasoning notes that the justices rejected Minnesota’s argument that state law could redefine the owner’s property interest in equity. The Court held that longstanding principles of property law recognize a separate interest in surplus value, and that government cannot erase that interest simply by statute. A detailed discussion of the ruling explains that the Supreme Court in Tyler v. Hennepin concluded that when a local government takes a home at a property tax foreclosure and keeps more than what is owed, it commits a taking. The analysis of how the Supreme Court Stops in property tax foreclosures summarizes that holding.
Advocates who had long campaigned against home equity theft saw Tyler as a turning point. An overview of their campaign describes how they challenged laws in several states that allowed counties to keep the full value of tax-foreclosed homes. The description of their effort notes that the Supreme Court declares home equity theft unconstitutional in Tyler v. Hennepin County, and that the ruling means states can no longer allow local governments to keep more than a taxpayer owes. That summary appears in a broader project titled Ending Home Equity Theft, which tracks reforms following the decision.
In response, several states have begun revising their tax foreclosure statutes to provide former owners with a right to claim surplus proceeds. Legal analyses point to New York as one example, where lawmakers and courts have been reassessing procedures in light of Tyler. Other states have faced litigation from homeowners who lost properties years earlier and now argue that the Constitution entitles them to compensation for equity that counties kept.
Leo’s been tracking game and tuning gear since he could stand upright. He’s sharp, driven, and knows how to keep things running when conditions turn.